|
Retire Early
Lifestyle
Retirement; like your parents, but way cooler

|
In 1991 Billy and Akaisha Kaderli retired at the age
of 38. Now, into their 4th decade of this
financially independent lifestyle, they invite you
to take advantage of their wisdom and experience. |
|
Now
What?
Billy Kaderli
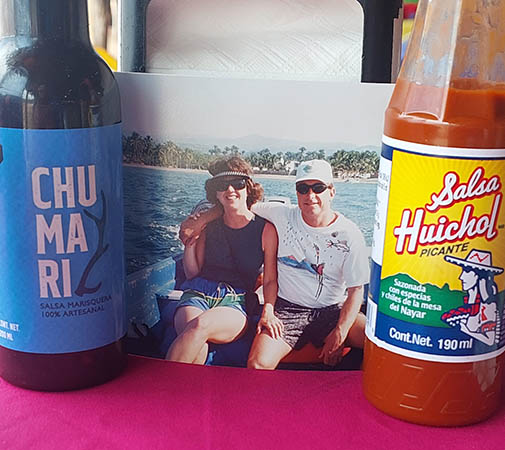
The person I shared it
with.
How do you spend a growing —
and, to me, comfortable — net worth when the person you shared it with is gone?
Akaisha and I did well with
our investments, much like those of you who started early and let the markets
work for you. Congratulations. I have spoken with younger investors and stressed
that the greatest asset anyone can have is time.
Today, as you read in my
recent post, time is no longer on my side.
In our last few years of
travel we spent more on housing and restaurants, and our spending still remained
a small percentage of our net worth. After Akaisha’s breast cancer treatments
and her final send-off, the money is still growing faster than we could spend
it.
This seems to be an issue for
other early retirees from my generation.
Some of you know from past
articles that we created a money machine four decades ago, and it’s working. It
becomes an exponential math explosion. I’m not bragging. It’s a fortunate
position to be in — just like a lot of you.
We started this adventure in
January 1991, when the S&P 500 closed at 312.49. You can do the math. We’ve
ridden the ups and downs, including two 50% drops, several 20% bear markets, and
new all-time highs. We stayed the course by keeping our spending in check.
Today I have a different kind
of problem. I need to spend more, yet I’m quite comfortable with my current
lifestyle. I’m not interested in wasting money just to spend it.
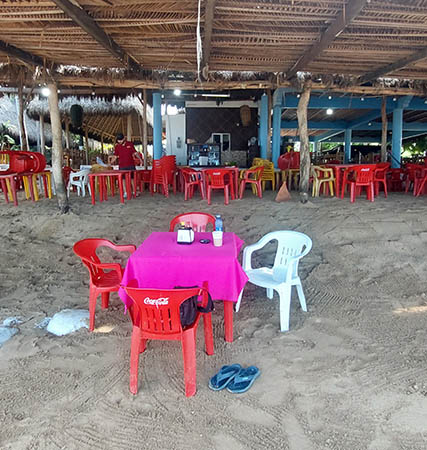
A table that used to be
for two.
Sure, I could blow money on
private planes. We’ve done that twice, and both times it was worth it — but
those were short flights. Flying private to Asia is a stretch… or is it? Phoenix
to Bangkok one-way is around $300,000. That would certainly be a story, but it’s
more than I spend in a year. I didn’t look into it deeply, and I’m sure there’s
more than one seat. Six people would be ideal, bringing it down to about $50,000
per person. Something to think about, but I doubt even my wealthy friends would
fly private to Asia. It’s just too big of a leap.
Heck, I couldn’t find anyone
to join me on that 204-foot sailboat across the Atlantic, and that was very
reasonably priced. Then again, that’s a slim number of people who would be
interested in a trip like that — and I’m not ready for it either. With a little
encouragement, though, I probably could have been talked into it.
When I consider what I’ve
written before about longevity — and how many of those remaining years I’ll
still be able to travel — bigger experiences start to sound more appealing.
I don’t have children, and
I’m not trying to build a dynasty. I’d rather use the money well while I can.
What got me thinking about
all this was a conversation this morning with a traveler friend who is currently
in Europe. We talked via WhatsApp about loosening the purse strings while we’re
still able, while still getting value for the money spent.
So the question remains: Now
what?

Retire
Early Lifestyle appeals to a different
kind of person – the person who prizes their
independence, values their time, and who doesn’t
want to mindlessly follow the crowd.
HOME
Book Store
Retire Early Lifestyle Blog
About Billy & Akaisha
Kaderli
Press
Contact
20 Questions
Preferred
Links
Retirement
Country Info
Retiree
Interviews
Commentary
REL
Videos
|


