In 1991 Billy and Akaisha Kaderli retired at the age
of 38. Now, into their 4th decade of this
financially independent lifestyle, they invite you
to take advantage of their wisdom and experience.
On Monday, we drew the line in the sand. As we wrote in Liquidity
Weighed On Gold Trumping Real Yields, a close below 7,490
would make a test of the 200-day moving average more likely. By lunchtime
Thursday, the market had blown right through that support level and tested that
200-day average. There is no way to sugarcoat Thursday’s sell-off, with the S&P
500 falling 4.4% to 7,353.73, its worst day since the April 2025 tariff crash.
The Nasdaq 100 lost 6.4%. For the week, the index fell 2.7% to 7,376.86. That
leaves it 5.7% below the October 6 record and up 7.8% for the year.
What makes the week so jarring is the sequence.
Wednesday delivered
what Fortune called the best post-midterm election rally in 44 years, with the
S&P 500 up 1.6% to 7,688.62. Twenty-four hours later, roughly $3 trillion in
market value was gone. The semiconductor ETF (SMH) dropped about 11% on
Thursday, Micron and AMD each lost roughly 17%, and Nvidia fell 9%.
The midterm election catalysts were stacked on top of each other.. Democratic
wins in Texas, Georgia, Ohio, and Michigan put roughly 45% of planned data
center capacity in states likely to tighten the rules, according to Goldman
Sachs. Weak results from Qualcomm and Arm hit the chip complex. Asian markets
sold off overnight, and the selling spread to the power names that feed the
buildout. The politics
lit the match, but leverage supplied the fuel. As we noted in Friday’s
commentary, Oracle
Bought High, Sold Low, Goldman’s prime book showed hedge fund
gross leverage near 310%, close to a five-year high, after funds lost more than
3% in October.
Thankfully, Friday brought a partial reprieve, with the market holding key
technical support but just barely as the October payrolls report surprised to
the upside. Employment jumped by 165,000, exceeding expectations of 65,000, and
the unemployment rate fell to 4.1%. Furthermore, revisions added another 84,000
jobs to August and September, and hourly earnings rose 0.4%.
While the outcome of the midterm elections gave the market something to worry
about, unfortunately, Friday’s strong labor report keeps a December rate hike in
the conversation. That isn’t what a market leaning on lower rates wanted to
hear.
Nonetheless, chip stocks bounced on Friday, but the market, however, managed
only a 0.3% gain and faded from 7,444 to close near the session low.
Beneath the brutal headlines, the actual selling was narrower than it felt. The
equal-weight S&P 500 (RSP) beat the cap-weighted index by 1.7 percentage points.
Five of eleven sectors finished higher, led by Communication Services at 4.9%.
Energy was the worst performer, down 12%, as WTI crude fell 13% to $90.50 and
Brent slid back below $100. Gold gained 4.5% to $4,076, and the 10-year Treasury
yield eased to 4.86% from 4.93%. The VIX jumped from 19.4 to 28.2 on Thursday
before settling at 25.6.
The thread to follow into next week is whether Thursday was a “liquidation
event” or the start of a trend. Liquidations tend to exhaust themselves quickly,
usually within a few sessions once the forced sellers are finished, the margin
calls stop and the leverage that built up during the rally has been cleared out
of the system. Trends don’t. Tuesday’s CPI report will tell us which way rates
lean while the market sorts it out.
📈Technical Backdrop– MACD Turns
Up Just Below The Record
Thursday did real technical damage. The S&P 500 closed Friday at 7,376.86, below
its 20-day (7,658), 50-day (7,679) and 100-day (7,619) moving averages. It’s
holding just 0.7% above the 200-day average at 7,325. The 14-day RSI sits at 35
after touching 33.5 on Thursday, and MACD has rolled into a sell signal at −61
points against a signal line of −27.
Here’s where the “buy the dip” crowd has
some hope. Following the post-midterm election rally, Thursday’s close pushed
the market 3.1 standard deviations below the 20-day average. That is an extreme
that rarely lasts.
In Friday’s commentary, we found 27 prior cases since 1950 when the
index stretched this far below its 20-day average while holding above its
200-day average. One month later, the market was higher 23 times, with
a median gain of 2.4%.
In other words,
oversold readings with an intact 200-day average have historically produced a
bounce rather than
a crash.
The problem is that our own rules have already spoken. On Monday, we said a
close below 7,490 meant tightening stops and raising cash. On Wednesday, in Oracle
Sells Cheap Stock As Its Debt Window Narrows, we said that a
decisive close below $169 in the technology ETF (XLK) would have prompted us to
step aside from new tech buying. XLK closed Friday at $164.74, 3.2% below its
own 200-day average. While both triggers fired, that doesn’t mean we are selling
everything. It means the growth tranches we laid out last week are on hold until
the trend repairs.
Sector breadth explains why the index held up as well as it did. Seven of eleven
sectors are trading well above their 50-day averages relative to the S&P 500,
led by Health Care (10.6 points), Staples (9.9), and Discretionary (7.7).
Technology sits 8.6 points below with an RSI of 29, and semiconductors are 18%
under their 50-day.
As we discussed Thursday in The
Election Aftermath: Let The Market Finish Voting, Health Care
is more than 15% above its 200-day average, a stretch seen only twice since
2005. The defensive
trade is now as crowded as tech was in October. That cuts both ways.
Oversold tech is where any rebound has to come from, while stretched defensives
are where the next round of selling may start.
Pay close attention to Friday’s market action, as it is likely more important
than you think. The index opened near 7,378, rallied to 7,444, and gave it all
back into the close.
Sellers are still leaning on every bounce. Use any rally toward the
7,620 to 7,680 cluster, where the 100-, 20-, and 50-day averages converge, to
trim laggards, rebalance the defensive winners that have run too far, and
rebuild cash.
So what does that mean for next week? Start by holding core positions at target
weights, but don’t aggressively add more exposure yet. If the 200-day average
holds and semiconductors reverse, the advice to add exposure in small tranches
resumes. However, a decisive close below 7,316, July’s swing low, opens the door
to 7,200. That violation would shift our process toward the 2018 playbook of
raising cash and hedging portfolios more aggressively.
Support levels for the market matter most next week, and the 200-day average at
7,325 is crucial. If the market can hold that key support, then this past week
looks like a violent correction inside a bull market. Lose it, and the
conversation changes from “how high” to “how
much cash.”
🔑 Key Catalysts Next
Week
Next week, inflation will move the market, and, unfortunately, the timing
couldn’t be any more awkward. On Tuesday, the markets will get the October CPI
report, with the consensus calling for a 0.3% monthly gain. The good news is
that it is half of September’s 0.6% jump, with the core reading expected at
0.2%. Friday’s PPI follows, with consensus at 0.4% after September’s 1.3% surge.
After a 165,000
payroll print, a hot reading on either would push December hike odds higher just
as growth stocks can least afford it.
The bond market has a heavy week too. Treasury sells 3-, 10-, and 30-year debt
on Monday, Tuesday, and Thursday. The bond market closes Wednesday for Veterans
Day, while stocks stay open. Thursday afternoon’s budget statement will show how
October’s deficit is tracking, with consensus near $298 billion.
Fed speakers are everywhere. Vice Chair for Supervision Bowman speaks Monday,
Tuesday and Friday, Chicago’s Goolsbee speaks Monday and Thursday, Governor
Waller and Dallas’s Logan speak Tuesday, and Thursday brings Cleveland’s Hammack,
Governor Barr, San Francisco’s Daly and New York’s Williams. Williams carries
the most weight on policy. Listen for how each one weighs Friday’s jobs report
against Tuesday’s CPI.
Notably, earnings season is slowing considerably, although there are still some
important reports, like Nvidia, to come. However, the names reporting next week
go straight to this week’s selloff. Constellation Energy reports Monday before
the open. Its read on data center power contracts will be the first corporate
response to the midterm election results from Texas.
Then, after a brutal selloff this past week, CoreWeave reports Tuesday after the
close, a direct test of how the debt-funded
“neocloud” model holds up under pressure. Thursday after the close brings
Applied Materials, the best read on chip equipment demand, and Cisco, a check on
enterprise AI networking spend. Applied Materials matters twice over, since it
reports into a semiconductor group that our commentary this week already placed
in a bear market.
In other words, there is still significant risk to the technology sector next
week.
For now, Washington will fade into the background, but it won’t be quiet. The
lame-duck Congress returns to a December 11 funding deadline, and headlines
around the Sanders and Ocasio-Cortez data center moratorium bill will keep
hitting AI stocks even though it has no path past a veto. Texas can’t act until
its Legislature convenes on January 12, so any clarity there is still weeks
away.
From a market perspective, the single most market-moving event is Tuesday’s CPI.
A soft print gives the oversold bounce room to run toward the 50-day average. A
hot one is the asymmetric risk, because layered on a strong jobs report and a
fragile tech tape, it would challenge the 200-day average just as the market is
testing it.
💰 Midterm
Election Goes Blue: What Happens With Markets Now?
On Tuesday night, the “blue wave” turned
into something closer to a midterm election tsunami. Democrats took the House
and flipped seven Senate seats, including Texas, for what Forbes tallied as a
54-seat majority. Futures dropped overnight. AI data center names took the worst
of it, and then buyers showed up before the open. As we noted earlier this week
in Liquidity
Weighed On Gold Trumping Real Yields, the year after midterm
elections has been positive for the stock market in all 19 cycles since 1950.
The question is whether this result breaks that pattern. I don’t think it does,
but the reasons matter more than the base rate.
What A Democratic Congress Can Actually Do To The AI Trade
Okay, with that recap, let’s start with the fear, because it’s real. Democrats
ran on electricity bills, and the data center was the villain. Bernie Sanders
has called for a moratorium on new construction. Elizabeth Warren opened an
investigation into hyperscaler power deals, and a voluntary ratepayer bill
already cleared the House in September. Before the vote, Wells Fargo’s Ohsung
Kwon warned that a Democratic win in the Texas governor’s race, the heart of the
data center buildout, was the left-tail risk for the AI trade. Texas got that
outcome.
The bigger threat sits
outside Washington. Republicans lost the governor’s mansions in Texas,
Georgia, Ohio, Michigan, and Nevada. Goldman Sachs estimates that the states
likely to tighten data center rules hold roughly 45% of planned U.S. capacity,
with Texas alone accounting for about a quarter. Virginia, home of
“Data Center Alley,” already has moratorium bills moving ahead of its
January 13 session.
Permits, zoning, and utility rules are set at the state level.
This is where the risk to the
capex story could actually slow.
It’s also why the selling hit the levered
“neoclouds” while Alphabet, Apple, Microsoft and Amazon all traded higher
during Wednesday’s trading session.
However, Texas is also
less of a shock than the headlines suggest. In August, Governor Abbott
ordered an audit of every data center in the grid queue and, in September,
halted the issuance of state environmental permits. What changed Tuesday is the
exit door. Governor-elect Gina Hinojosa says the pause will remain in effect
until the Legislature acts, and Democrat Vikki Goodwin’s upset of Dan Patrick
for lieutenant governor puts a pause supporter in charge of the Texas Senate’s
agenda.
In Texas, the legislative session runs from January 12 through May 31, 2027. Of
course, with everyone now watching what happens in Texas next, the market will
take its cues from its decisions.
However, for
investors, the most realistic risk is a delay in data center projects, not
cancellations.
Most crucially, when
looking at earnings for data center players, projects that already have power,
permits, and steel keep building. However, it is the projects without
them that are either delayed by a year or move to friendlier states like
Louisiana. Jefferies summed it up as demand moving right, not away. To wit:
“The
question will be how much does this alter fundamentals.” Amit
Daryanani, Evercore ISI
Gridlock Has A Better Record Than Either Party
During every election cycle, there is invariably some media outlet running a
narrative that markets do better under one party than the other. The problem is
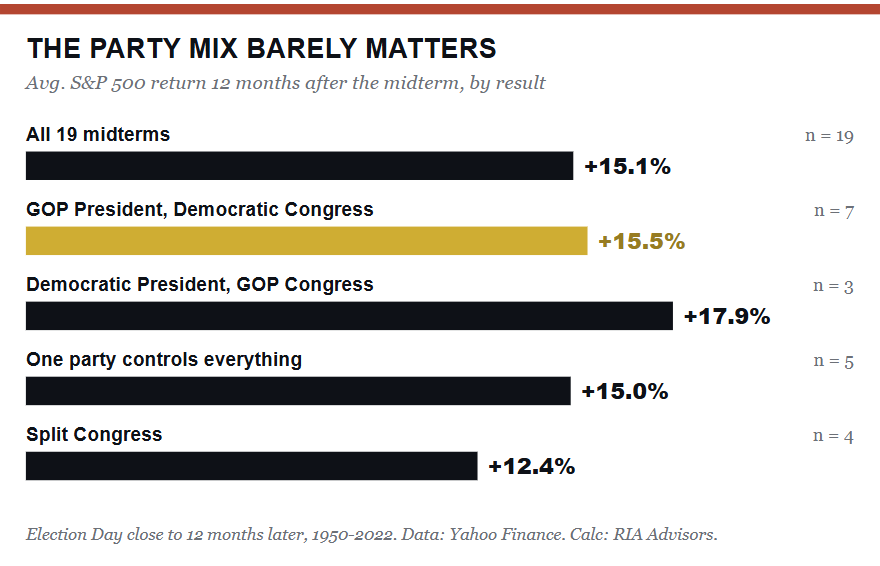
that the data doesn’t support it. I sorted the 19 midterm elections since 1950
by the government each one produced, from unified control to a split Congress,
and then measured where the S&P 500 stood twelve months after the vote. The
setup we now have, a Republican President facing a Democratic Congress, averaged
15.5% across seven cases. The full set of 19 averaged 15.1%. Every configuration
was positive on average, and not one of the 19 cycles finished the following
year lower.
Such is the real lesson. The midterm election cycle does the work, not the party
that wins it. Throughout the history of all four-year presidential cycles,
midterm election years tend to see the deepest drawdowns. Such is why, by
Election Day, much of the “uncertainty” is
already priced in. Once the votes are counted, that discount unwinds regardless
of the map’s color. Investors
don’t need a friendly Washington. They need a predictable one, and gridlock is
about as predictable as Washington gets.
Seven Times Before, And The One That Stung
Here are the seven midterm elections that handed a Republican President a
Democratic Congress, measured from the Election Day close. The averages look
terrific, with the index up 10.7% after three months, 17.5% after six, 20.1%
after nine, and 15.5% after a full year, which is better than the 19-cycle
average at every horizon. All seven were higher at every checkpoint.
However, it is
important to understand that“averages”hide the path, and the
path is what investors actually live through. A good example occurred
in 1986 when Democrats retook the Senate under Reagan. Over the next 9 months,
the market gained 28.4%. Then October 1987 arrived, a 33% drawdown hit within
the year, and the twelve-month gain shrank to 1.1%.
More recently, the closest analog to 2026 is 2006, when Democrats flipped both
chambers under a second-term republican president, George Bush. Over the next 12
months, the market gained 6.7%, but the bull market peaked eleven months after
the vote. Seven observations are a small sample, so treat this as a tilt in the
odds rather than a promise.
Impeachment And Shutdowns Make Noise, Rarely Bear Markets
Unfortunately, the one thing that the markets will likely have to deal with is
the resurgence of impeachment actions against the President. The incoming class
includes a louder populist and, in a few cases, openly
“socialist” wing; the relationship with
the White House starts out hostile, and Hakeem Jeffries has said Democrats
haven’t ruled impeachment in or out. A House majority can impeach. Removal takes
67 Senate votes, and Democrats hold 54. So while an
“impeachment” may cause short-term market
turmoil, a full removal is highly unlikely.
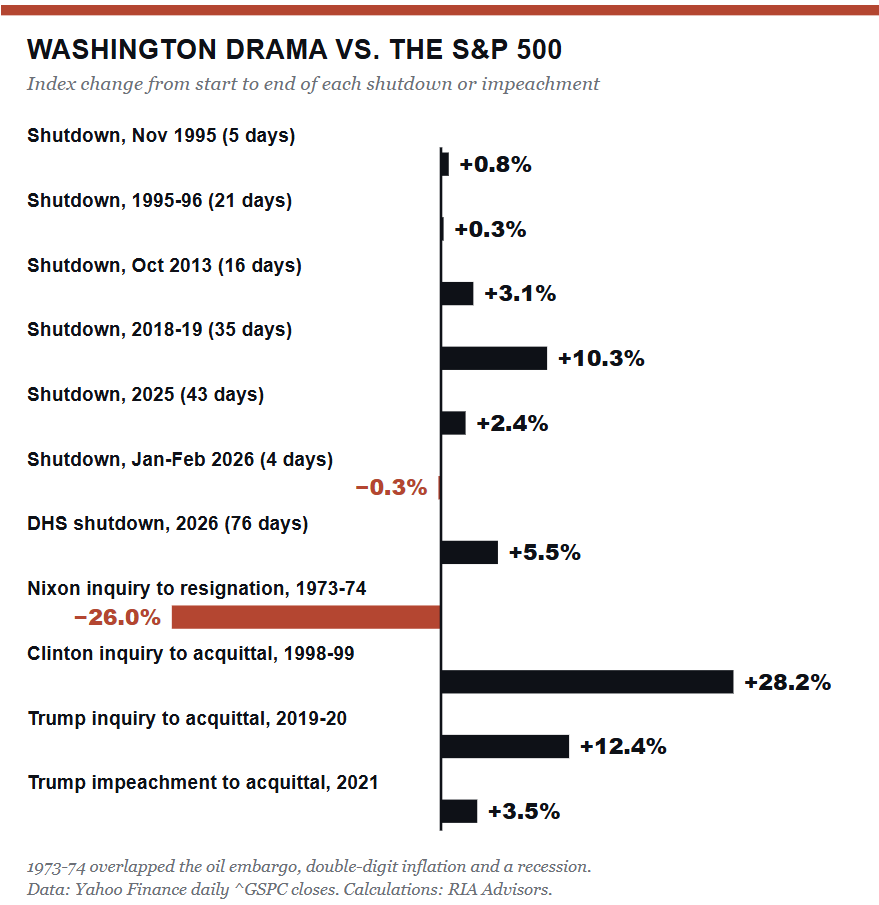
However, how would the market likely respond to an attempt at impeachment?
Less than you’d think. The Clinton impeachment coincided with a 28% rally, and
stocks gained 12% from the opening of the first Trump inquiry to the acquittal.
The most likely risk of the post-midterm election configuration is a government
shutdown. While government shutdowns are used for political positioning and
media attention, they have very little impact on the market itself. The S&P 500
rose during every lapse since 1995 except a four-day gap this January. That
includes the 35-day closure in 2018-19 and last year’s 43-day shutdown.
The exception is Nixon. Stocks fell 26% from the opening of the House inquiry in
October 1973 to his resignation the following August. That stretch also brought
the Arab oil embargo, double-digit inflation, and a recession. Washington
didn’t cause that bear market. The economy did, and political chaos rode along.
The nearer test is December 11, when the stopgap funding bill expires, one day
after ERCOT files its Texas data center audit. A defeated majority has to pass
something in the lame duck, and a short lapse is plausible. Such is the nature
of a Congress with nothing left to lose. I’d expect noise rather than anything
that ends the bull market.
The Bond Market Is Betting On Slower Growth, Not Bigger Deficits
Someone will tell you that a Democratic Congress means a spending spree and a
“bond vigilante” revolt. The bond market
disagreed on Wednesday. By midday, the 10-year Treasury yield had slipped about
five basis points to roughly 4.90%, and the 2-year and 30-year followed it
lower. That isn’t what a market bracing for a deficit blowout looks like.
Start with spending.
Democrats would like to spend more, and Pimco’s Libby Cantrill expects deficits
to widen no matter who controls Congress. However, the same veto math
that protects the data center buildout also blocks any large new spending
program. The likely path is two years of stopgaps, standoffs and a debt ceiling
fight that Reuters reports probably won’t bite until late 2027.
Gridlock won’t shrink
the deficit. It does keep it from accelerating.
For the market, growth matters more. Currently,
ING estimates that
AI-related investment accounts for roughly 33% of U.S. economic growth this
year. Wells Fargo figures that for every 10% cut to Texas data center
projects, it will trim total AI capex by about 1.6%.
Therefore, if state
permitting freezes, or federal scrutiny slows the data center buildout,
the economy loses its biggest engine.
For the bond market,
slower growth means lower yields. I’ve long argued that debt and
deficits are ultimately disinflationary, because unproductive borrowing erodes
growth over time. This sets up a trap that Democrats are potentially walking
into. Since political parties can’t, and have no desire, to cut the deficit, any
actions that slow the capex cycle will increase the economic drag that is
already present. Such an outcome could be perilous heading into the 2028
Presidential election.
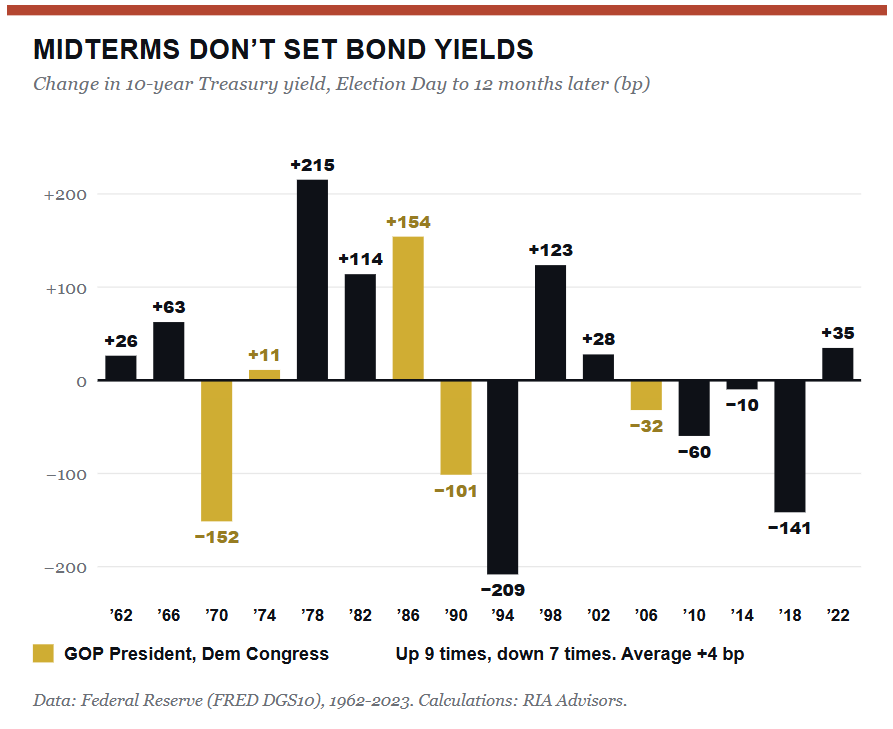
However, history agrees that midterm elections don’t set interest rates. Over
the last 16 midterm elections since FRED’s daily 10-year data begins in 1962,
the yield rose over the following year nine times and fell seven times, for an
average change of just 4 basis points.
Most notably, given the current Congressional makeup, interest rates under a
Republican President facing a Democratic Congress fell in three out of five
cases. As we have repeatedly stated, it is economic growth, inflation, and the
Fed that drive yields. Congress mostly supplies the noise.
There is one place that you should watch more closely, and that is the long end
of the yield curve. The 30-year sits near 5.3%, and a shutdown standoff or debt
ceiling brinkmanship can add term premium in a hurry, even when the growth
outlook argues for lower rates.
I would treat a
fiscal-driven spike in long yields as an opportunity to add duration rather than
a reason to run from bonds.
The views expressed by Lance Roberts are not
necessarily those of RetireEarlyLifestyle.com
Billy and Akaisha Kaderli are
recognized retirement experts and internationally published authors on
topics of finance, medical tourism and world travel. With the wealth of
information they share on their award winning website RetireEarlyLifestyle.com,
they have been helping people achieve their own retirement dreams since
1991. They wrote the popular books, The
Adventurer’s Guide to Early Retirement and Your
Retirement Dream IS Possible available on their website
bookstore or
on Amazon.com.
Retire
Early Lifestyle appeals to a different
kind of person – the person who prizes their
independence, values their
time, and who doesn’t want to mindlessly
follow the crowd.